
Retirement plan decisions involving alternative assets require careful analysis, clear documentation, and ongoing oversight. As digital assets and other nontraditional holdings receive greater attention, retirement plan committees face an important question: how can they demonstrate that a decision followed a prudent process, regardless of the asset ultimately selected?
The concept of a retirement fiduciary safe harbor addresses this question through a process-oriented approach. Rather than endorsing a particular asset class, proposed protections emphasize how fiduciaries evaluate available information, assess material risks, document their reasoning, and review decisions over time.
On March 30, 2026, the US Department of Labor announced a proposed regulation addressing fiduciary duties when selecting designated investment alternatives for participant-directed retirement plans. The proposal identifies performance, fees, liquidity, valuation, performance benchmarks, and complexity as factors requiring objective, thorough, and analytical consideration. The proposal is not blanket approval of alternative assets, and its legal status should be verified before anyone relies on it.
Understanding Process-Based Fiduciary Protections
A process-based safe harbor focuses on the quality of a decision-making framework. It recognizes that responsible governance requires more than selecting an asset that later performs well. Decision-makers must establish what they considered, which risks they identified, and why their conclusions were reasonable based on the information available at the time.
For retirement committees, this distinction matters because market outcomes are uncertain. An asset can decline despite careful evaluation, while a poorly documented decision can appear successful during favorable market conditions. Neither outcome alone establishes whether the underlying process was prudent.
A structured framework therefore connects risk management with evidence, accountability, and repeatable procedures. It also provides a consistent basis for examining alternatives with different liquidity characteristics, valuation methods, operational requirements, and levels of complexity.
The central principle is straightforward: evaluate the decision-making process independently of any assumption about future market performance.
Why Documentation Matters
Documentation creates a record of how a decision developed. It can show whether a committee reviewed relevant information, challenged assumptions, considered competing approaches, and addressed material uncertainties before reaching a conclusion.
Useful records may include:
- Written evaluation criteria established before the selection process.
- Research supporting the initial assessment.
- Meeting minutes recording questions, disagreements, and conclusions.
- Reviews of costs, liquidity restrictions, valuation practices, and operational dependencies.
- Records of conflicts of interest and the steps taken to address them.
- Scheduled review dates and documented reasons for retaining or reconsidering a selection.
These records should reflect the actual process rather than reconstruct a justification after a decision has been made.
Effective investment analysis also requires distinguishing verified information from estimates and assumptions. For example, a committee evaluating a privately valued asset might record the source of its valuation, the frequency of updates, the assumptions used, and the limitations of available comparisons.
This level of detail makes the reasoning easier to examine later. It also helps committees identify gaps in their procedures and determine whether additional information is needed.
Six Factors That Deserve Structured Review
The Department of Labor’s March 2026 proposal identifies six factors for consideration when selecting designated investment alternatives. Each calls for a documented assessment appropriate to the characteristics of the option under review.
1. Performance
Historical results can provide context, but they do not establish what will happen next. Evaluation should identify the measurement period, relevant comparison benchmarks, calculation methods, and limitations of the available data.
Where reported results depend on estimates or infrequent valuations, the committee should document those limitations rather than treat the figures as directly comparable to more frequently priced assets.
2. Fees and Expenses
Costs can affect the amount remaining in a retirement account over time. A thorough review identifies direct charges, indirect expenses, administrative costs, and other material fees.
Comparisons should account for differences in structure and services. A lower headline fee does not necessarily represent a lower total cost, particularly when certain expenses are disclosed separately.
3. Liquidity
Liquidity concerns how readily an asset can be converted into available funds under stated conditions. Reviewers should examine withdrawal restrictions, redemption schedules, settlement periods, and circumstances that could delay access.
This is especially relevant when an underlying asset cannot be sold quickly without affecting the available price.
4. Valuation
Valuation procedures determine how an asset’s reported value is established. Committees should understand whether prices come from observable transactions, independent assessments, models, or estimates.
They should also document how often valuations are updated and how uncertainty is communicated. A reported value may not equal the amount ultimately realized in a transaction.
5. Performance Benchmarks
Benchmarks provide a reference point for interpreting results. Their usefulness depends on whether they reflect the asset’s characteristics, risk profile, time horizon, and valuation practices.
An unsuitable benchmark can distort comparisons. The rationale for choosing a particular reference should therefore be recorded and periodically reconsidered.
6. Complexity
Complex structures can make costs, liquidity restrictions, valuation methods, and operational dependencies harder to assess. Reviewers should establish whether they have sufficient information and appropriate internal capacity to understand these features.
When material questions remain unanswered, the committee should document the uncertainty and determine whether further analysis is necessary before proceeding.
Together, these factors create a consistent framework for portfolio management oversight without prescribing which assets a retirement plan should select.
Turning Evaluation Criteria Into a Repeatable Process
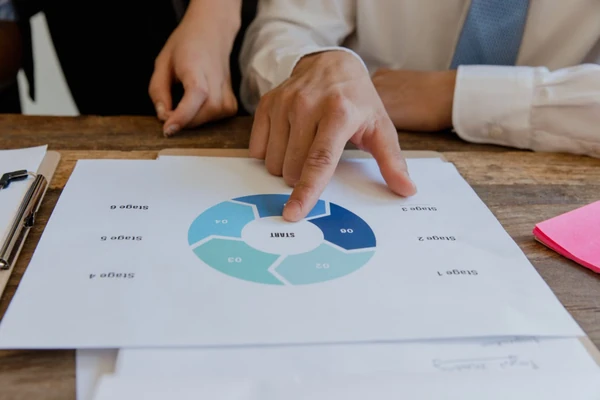
A written framework becomes more useful when it translates broad principles into practical steps. A retirement committee can organize its work around five stages:
1. Define the criteria. Establish the questions, evidence requirements, and evaluation standards before reviewing individual options.
2. Gather supporting information. Collect relevant documentation, identify information gaps, and assess the reliability of each source.
3. Evaluate material risks. Examine costs, liquidity, valuation uncertainty, complexity, and operational dependencies in context.
4. Record the rationale. Document the findings, alternatives considered, unresolved questions, and reasons supporting the conclusion.
5. Schedule ongoing reviews. Set review intervals, assign responsibilities, and identify events that warrant an earlier reassessment.
This workflow supports investment strategies grounded in preparation and accountability. It also gives committees a defined method for revisiting decisions when circumstances change.
A record should distinguish between information available when the decision was made and facts that emerged later. That distinction helps prevent hindsight from replacing an assessment of the original process.
Applying Governance Principles to Digital Assets
Digital assets introduce specific operational and valuation questions that may require additional scrutiny. Cryptocurrency markets can experience substantial price fluctuations, while trading activity, custody arrangements, network conditions, and platform dependencies may affect transaction execution and asset access.
A documented digital asset strategy should therefore consider how these characteristics fit within the broader governance process. Relevant questions include who controls access credentials, how custody arrangements are assessed, what procedures apply to operational disruptions, and how transaction records are reconciled.
Committees should also examine how asset values are determined, how market data is sourced, and how material uncertainties are communicated. These questions concern operational readiness and the quality of available evidence, not whether digital assets are inherently appropriate for a retirement plan.
For example, a committee might encounter a digital asset product with limited operating history and valuation data that varies across platforms. A structured review would record those limitations, assess the reliability of the available information, and explain how unresolved issues affected the evaluation.
Such an approach to digital asset management helps maintain consistency between the review framework and the specific risks presented by the asset under consideration.
The Kenson Perspective
Kenson Investments approaches the digital asset space through an emphasis on education, transparency, preparation, and awareness of associated risks. These priorities are relevant to governance discussions because decisions involving emerging technologies require a clear understanding of available information, operational limitations, and uncertainty.
Within a structured risk management framework, documentation can help separate observable facts from assumptions and identify questions requiring further investigation. Education also supports clearer discussions about blockchain systems, custody arrangements, market volatility, and the practical considerations associated with digital assets.
Kenson’s educational focus does not establish that a particular asset is suitable for a retirement plan, nor does it replace the responsibilities of plan fiduciaries or qualified legal and regulatory review. The purpose is to support greater understanding of the underlying systems and the questions that informed decision-making should address.
This measured approach aligns with a broader principle of capital stewardship: establish a clear process, acknowledge uncertainty, and avoid treating any market outcome as assured.
A Governance Framework That Remains Accountable
Process-based protections place attention on how decisions are made, recorded, and reviewed. For retirement committees, the practical work involves setting evaluation standards, examining material factors, documenting conclusions, and maintaining procedures that respond to changing conditions.
A digital asset strategy developed within this framework should remain specific about its assumptions, limitations, and operational requirements. The same discipline applies to other alternative assets, each of which can present distinct costs, liquidity constraints, valuation challenges, and governance considerations.
The proposed federal framework should not be interpreted as an endorsement of any particular asset or as a substitute for applicable legal requirements. Committees should review the final regulatory status, consult qualified legal counsel where necessary, and ensure that their procedures reflect the rules governing their specific retirement plans.
Ultimately, a defensible process is one that can be explained clearly, supported by contemporaneous records, and reviewed as circumstances evolve. That foundation supports more consistent governance without promising any particular market result.
Learn More About Digital Asset Education
Readers interested in Kenson Investments’ approach to digital assets can learn about the company’s background, explore its digital asset education resources, or connect with a Digital Asset Specialist to discuss general digital asset goals.
About the Author
Daniel Mercer is a fictional financial governance writer who covers retirement plan oversight, fiduciary documentation, digital asset operations, and emerging technology risk. His work focuses on explaining complex regulatory developments in accessible language and examining how structured review procedures support accountability. This biography is illustrative and does not represent verified credentials or employment history.
Disclaimer
The information provided on this page is for educational and informational purposes only and should not be construed as financial advice. Cryptocurrency assets involve inherent risks, and past performance is not indicative of future results. Always conduct thorough research and consult with a qualified financial advisor before making investment decisions.
The cryptocurrency and digital asset space is an emerging asset class that has not yet been regulated by the SEC and US Federal Government. None of the information provided by Kenson LLC should be considered as financial investment advice. Please consult your Registered Financial Advisor for guidance. Kenson LLC does not offer any products regulated by the SEC, including equities, registered securities, ETFs, stocks, bonds, or equivalents.